401(k) & BUSINESS RETIREMENT PLANS
Simplify Your Retirement Plan.
A retirement plan should work for your business, your employees, and you.
Bonfanti Investment Services provides independent guidance to business owners and plan sponsors seeking to better understand, evaluate, and improve their company retirement plans.
Whether you're reviewing an existing 401(k), considering a new plan, or simply wondering if what you have today is still competitive, we'll help you understand your options and make informed decisions.
Is Your Retirement Plan Working As Hard As It Should?
A good retirement plan review should help answer three basic questions:
Can we save your business money?
Review plan-level costs, plan design, employer contributions and the overall structure to identify opportunities for greater efficiency.
Can we save your employees money?
Evaluate participant costs, investment expenses and the investment lineup to determine whether employees are receiving competitive value.
Can we save you time and administrative headaches?
Look at administration, service, payroll integration and the various parties involved in operating the plan to identify ways to make your job easier.
Sometimes a review uncovers meaningful opportunities for improvement. Sometimes it confirms that the plan you already have is working well.
Either way, you should understand what you're paying for, how your plan works, and whether it continues to fit your business.
What We Review
A company retirement plan has a lot of moving parts. We look beyond the investment lineup to understand how the entire plan is working for the business, its employees, and the people responsible for managing it.
Plan Costs & Fees
Review employer expenses, participant fees, investment costs, and other plan-level charges to better understand what the plan is actually costing.
Investments
Evaluate the investment lineup, fund expenses, diversification, target-date options, and whether lower-cost or more appropriate alternatives may be available.
Plan Design
Review eligibility, employer contributions, matching or profit-sharing formulas, vesting, Safe Harbor options, and whether the plan design still fits the goals of the business.
Fiduciary Process
Evaluate the process used to select and monitor investments, document decisions, and fulfill the plan sponsor's ongoing fiduciary responsibilities.
Administration & Payroll
Look at how payroll, recordkeeping, third-party administration, and the advisor work together—and where unnecessary complexity or administrative headaches may exist.
Employee Experience
Consider enrollment, education, communication, investment support, and how easy it is for employees to understand and use the benefit being provided to them.
As Your Business Evolves, Your Retirement Plan Should Too.
A successful business rarely looks the same five or ten years after it starts. Employees are added, profitability changes, tax considerations become more important, and attracting and retaining good people may become a bigger priority.
The retirement plan that worked at one stage of the business may not be the right plan for the next.
GETTTING STARTED
Creating a retirement savings strategy
IRA / SEP
OWNER ONLY
Building retirement savings
SEP / Individual 401(k)
FIRST EMPLOYEES
Offering a meaningful benefit
SIMPLE IRA / 401(k)
GROWING TEAM
Balancing employee benefits and owner goals
Traditional / Safe Harbor 401(k)
ESTABLISHED BUSINESS
Optimizing plan design and savings opportunities
401(k) / Profit Sharing / Advanced Plan Design
There isn't one retirement plan every successful business eventually reaches. Businesses can skip stages, stay with the same type of plan for years, or move in a different direction entirely. What matters is whether the plan still fits the business.
Has anything changed?
Your employees? Your profitability? Your goals? The amount you want to save? The value you want the plan to provide?
If the business has changed, it may be worth asking whether the retirement plan should change with it.
The Right Plan Starts With the Right Structure.
Retirement plans involve several different roles—payroll, recordkeeping, administration, investments, and advice. Sometimes those services are bundled together. Sometimes they are handled by different providers.
Our job is to help determine which structure makes the most sense for your business—not to force every company into the same solution.
Payroll & Administration
How contributions, employee data, testing, filings, and day-to-day plan administration are handled.
Recordkeeping & Technology
The platform employees use to access the plan, track investments, enroll, and manage their accounts.
Independent Advice
Plan design guidance, investment oversight, fiduciary support, benchmarking, and ongoing review.
You don’t have to change everything to improve something.
Sometimes the existing payroll relationship works well. Sometimes the current recordkeeper is competitive. Sometimes a change is worth considering. We evaluate each part of the plan before recommending what—if anything—should change.
Flexible Recordkeeping Options
We are not tied to a single 401(k) recordkeeper. When a change makes sense, we can evaluate multiple platforms based on plan size, service needs, payroll integration, investment flexibility, cost, and employee experience.
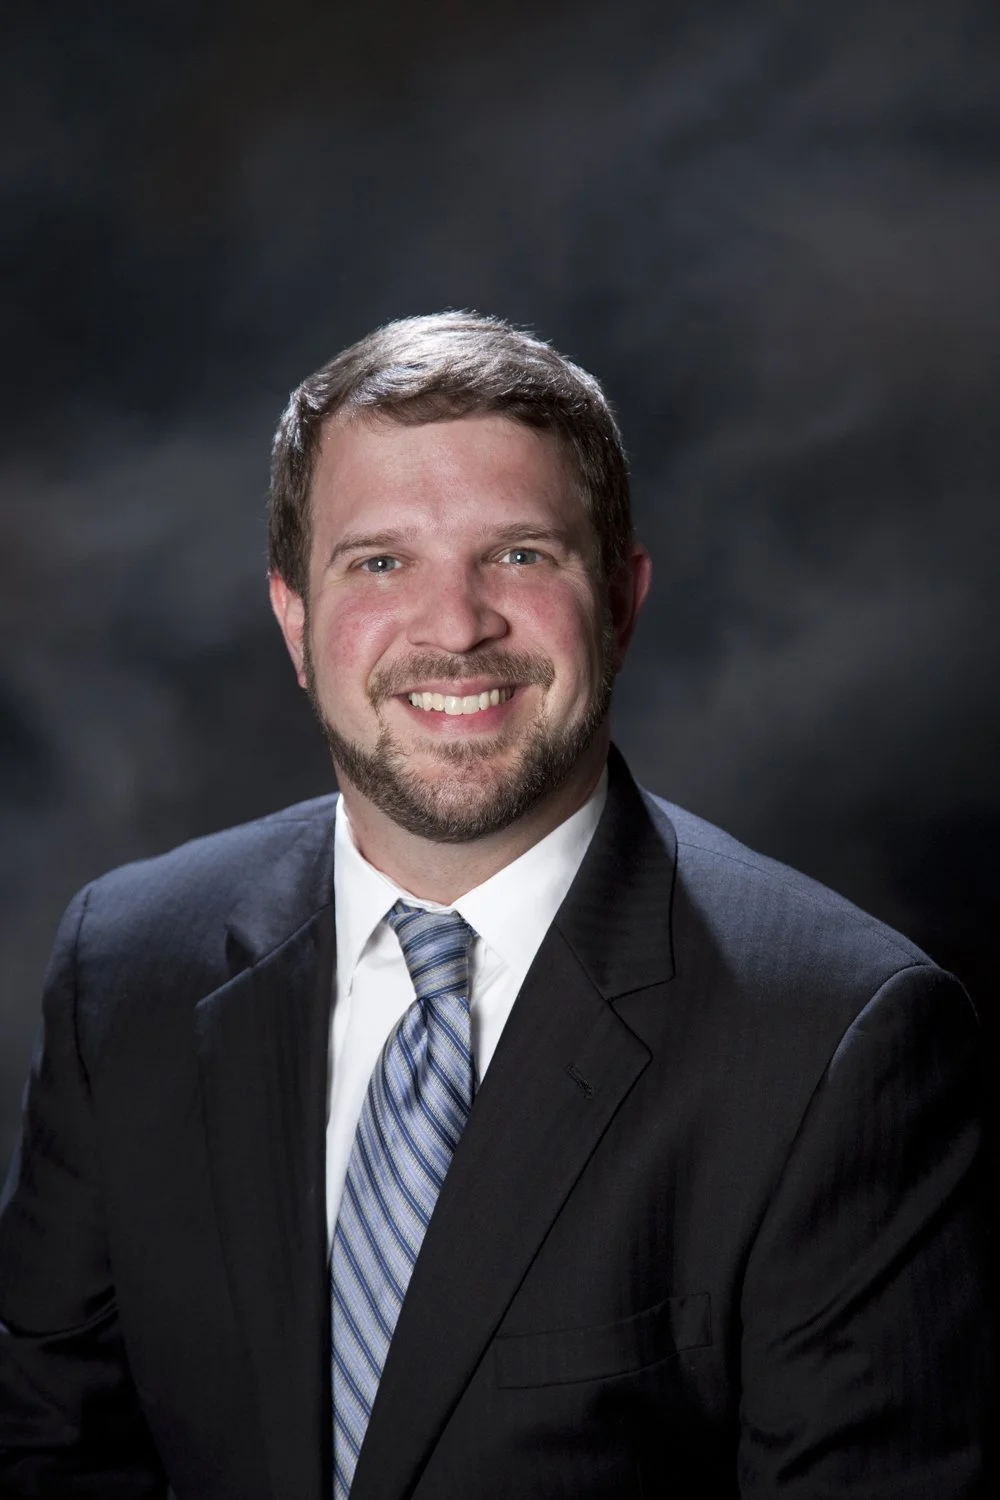
Independent Advice. Personal Relationships.
For more than 20 years, Bonfanti Investment Services has helped individuals and families make informed financial decisions through independent financial planning and investment management.
We bring that same approach to business retirement plans—helping employers understand what they have, evaluate their options, and make decisions based on what is right for their business and their employees.
Michael Bonfanti, CFP®, CPFA®
Founder & Investment Advisor
Prairieville, Louisiana
Have an existing plan? A conversation can simply start with a second look at what you already have.